Insurance DataLab Compresses a Thousand Insurers into One Comparable Ledger, Turning Regulatory Pressure into Boardroom Clarity
The Silicon Review
Ask an underwriting director how their combined operating ratio compares with peers and the honest answer is often a guess dressed as a number. Ask a broker's security committee whether an insurer partner's solvency position has deteriorated and the answer may arrive weeks after the decision mattered. Insurance DataLab was built on the premise that the UK general insurance market's performance data exists in fragments, and that assembling those fragments into a like-for-like ledger is a defensible business.
The platform covers all UK, Ireland and Gibraltar-regulated general insurers and Lloyd's Syndicates, plus the financial performance of UK brokers and MGAs, with data on more than 1,000 insurance companies and brands and providers writing more than £100 billion in annual gross written premium. Each insurer's and syndicate's performance is broken down by business line, with sector-specific market averages available for the product lines that matter to a given client.
That granularity serves four distinct audiences: insurers benchmarking underwriting and solvency, brokers evidencing product governance, MGAs vetting capacity providers, and investors evaluating acquisition targets. The regulatory tailwind is considerable. Consumer Duty obligations require firms to demonstrate fair value and good customer outcomes with evidence, and evidence requires comparative data. Insurance DataLab is owned and operated by MAD Financial Media Limited, and its leadership includes Matt Scott, Co-founder and Chief Product Officer, an actuary-trained former insurance journalist.
Four Pillars, One Comparable Ledger
The architecture of the platform is built around what the company calls four pillars: claims, complaints, solvency, and underwriting. These are not unrelated datasets. They are combined into a proprietary Insurer Performance Index and surfaced through a RAG-rating system that gives boards a single view of relative standing. The commercial logic follows the buyer. Underwriting benchmarking sells to strategy and finance teams seeking peer-relative cost and reserving insight. Solvency assessment sells to capital managers needing evidence for year-end positions. Regulatory compliance sells to complaints and customer experience teams facing Consumer Duty reporting. Board-level management information sells to executives who need fewer pages, not more.
Where Decisions Become Revenue
The revenue influence is clearest in three decision types. The first is partner selection. For MGAs and brokers, choosing a capacity provider or insurer partner is a risk decision with direct financial consequence, and the platform's Security Committee-in-a-Box offering converts performance data into a governance record. The second is M&A. Broker and MGA consolidation continues, and the platform supports target identification and due diligence with financial and operational benchmarking. The third is internal performance management, where benchmarking against peers helps firms set KPIs and, in the broking market, prepare for a future sale. Each of these is a decision that carries a cost of error measured in capital or regulatory exposure. That is why benchmarking data sustains subscription economics rather than one-off purchases: the questions recur quarterly, annually, and at every board meeting.
The Discipline of Like-for-Like
Insurance DataLab's credibility rests on comparability. Comparing insurers requires normalizing for business line mix, and the platform's breakdown by line and sector-specific averages addresses the objection that raw combined ratios mislead across different books. The same discipline applies to complaints data, segmented by company, product line and complaint type, which allows root-cause identification rather than aggregate complaint counts.
Matt Scott's background informs this orientation. As insight editor of Insurance Times, he authored the annual Top 50 Insurers and Top 50 Brokers reports, and his actuarial training at Aon provides the technical vocabulary to interrogate the numbers rather than merely publish them. Product development and market analysis sit under his direction, which is a useful signal about how the company weights methodology against presentation.
What Comparative Intelligence Is Actually For
The UK general insurance market is not short of data. It is short of comparability that survives scrutiny. Regulatory pressure has made the difference expensive: a firm that cannot evidence how its outcomes compare with the market is exposed, and a firm that can is advantaged. Insurance DataLab's position depends on maintaining coverage breadth, methodological consistency and enough timeliness to matter in a decision cycle. For a market where a thousand insurers and brands compete on thin margins, a reliable ledger of relative performance is infrastructure, not commentary.
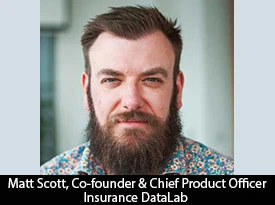
Matt Scott, Co-founder and Chief Product Officer
"Compare the underwriting performance of all UK, Ireland and Gibraltar-regulated general insurers and Lloyd's Syndicates on a like-for-like basis."
Company description: Insurance DataLab is recognized as an award-winning market intelligence platform, with benchmarking insights produced on the performance of insurers, Lloyd's Syndicates, MGAs and broking firms. Data on more than 1,000 insurance companies and brands is maintained, covering providers writing more than £100 billion in annual gross written premium. Comparative analysis across claims, complaints, solvency and underwriting is delivered to support compliance, partner oversight and strategic decisions.
Search Magazine
Latest Listings