BlueSnap Treats Payments Expertise as the Differentiator That Technology Alone Cannot Replace
The Silicon Review
Global payment infrastructure has become commoditized at the connection layer. Most platforms can process a card transaction. Far fewer can explain why a specific transaction declined in a specific market, route it through an alternate acquiring bank, recover the revenue, and document the outcome for the finance team. The distinction between processing a payment and understanding one determines whether a business expands internationally with confidence or absorbs losses it cannot diagnose. Research cited by BlueSnap indicates that 31 percent of companies selling internationally rely on four or more separate solutions to meet their global payment needs, producing fragmented visibility and compounding technical debt.
BlueSnap operates in that complexity. Powered by Payroc and headquartered with offices in Boston, London, Dublin, and Herzliya, the company delivers a Global Payment Orchestration Platform that consolidates payment processing, optimization, fraud prevention, chargeback management, compliance, and unified reporting into a single integration and account. Its platform is modular by design, allowing functionality to be activated or disabled by country, product, or issuer rather than requiring uniform configuration across every market.
What separates BlueSnap from platform-only competitors is stated in its own positioning: payments powered by people. The company maintains a team of Payments Experts who work alongside clients to design strategies, not just implement software. That combination of modular technology and human guidance addresses a pattern BlueSnap observes repeatedly, where businesses lack the internal expertise to optimize payment performance even when the tools are available. For organizations treating payments as a strategic function rather than a back-office necessity, that distinction carries direct revenue implications.
Global Connectivity as a Revenue Mechanism
BlueSnap's core infrastructure connects businesses to a global network of acquiring banks through Intelligent Payment Routing, with local acquiring available in 50 countries and 15 like-for-like currencies. The commercial logic is straightforward. Cross-border transactions carry higher decline rates because issuing banks treat them as elevated risk, and card networks apply cross-border fees that can reach an additional 2 percent on top of standard interchange. By processing domestically where possible and presenting transactions in the customer's local currency, BlueSnap reduces both decline exposure and fee leakage. For high-volume international merchants, that combination produces measurable improvements in authorization rates and net margin per transaction.
Embedded Payments as Platform Monetization
BlueSnap's Embedded Payments offering addresses software platforms seeking to monetize payments within their own products. Research cited by the company indicates embedding payments into a platform can increase value per customer by a factor of five. BlueSnap supports this through white-label payment solutions, fast merchant onboarding via API or hosted application, global payouts, and tailored risk management, allowing platforms to own the payment experience without building compliance infrastructure internally. Platforms retain control over pricing, customer communication flows, and branding while BlueSnap handles underwriting, compliance, and processing. For software companies evaluating payments as a revenue line rather than a cost center, that structure determines whether the initiative reaches market in months or stalls in development.
Invoicing and Billing as Cash Flow Infrastructure
BlueSnap's Invoicing and Billing solutions address accounts receivable inefficiency, which the company quantifies directly. Its research indicates managing a single invoice consumes 11 hours and involves 11 to 15 people, while 77 percent of companies report concern about cash flow tied to overdue invoices. BlueSnap's platform digitizes the quote-to-cash process through Accounts Receivable Automation, Subscription and Recurring Billing, Invoice Payments with embedded payment links, and Virtual Terminal capability. Pre-built integrations with Oracle NetSuite, Sage Intacct, QuickBooks, Microsoft Dynamics 365 Business Central, and Xero synchronize customer accounts, invoices, and payments automatically, allowing the ERP to remain the system of record. Reducing Days Sales Outstanding improves working capital without requiring additional financing, which for many businesses represents a larger financial gain than processing cost reduction.
Modularity as Operational Control
BlueSnap's architecture allows individual capabilities to be enabled by market, product, or issuer. A merchant can apply stricter fraud rules to specific product categories, activate 3-D Secure in the EU and UK, or offer SEPA only in Germany. That granularity matters because payment strategy varies by jurisdiction, and uniform global configuration typically produces either excessive friction in low-risk markets or insufficient control in high-risk ones. For payment operations teams, that configuration flexibility reduces the engineering effort required to support market-specific requirements.
The Growth Logic of Guided Payment Infrastructure
BlueSnap's expansion reflects sustained demand for payment infrastructure that combines global reach with advisory expertise. With local acquiring in 50 countries, pre-built ERP integrations, embedded payment capabilities, and a modular orchestration platform serving merchants, platforms, and software companies, the firm has established itself among the cloud payments companies worth watching in 2026. The commercial logic is direct: payment complexity increases with every market entered, and technology alone does not tell a business which markets to prioritize or why a specific corridor underperforms.
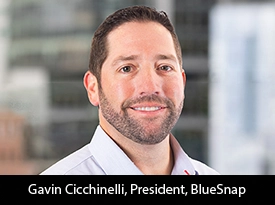
Gavin Cicchinelli, President