Helcim Rips Up the Flat Rate Playbook and Hands Merchants Wholesale Payment Pricing
The Silicon Review
Small business owners rarely know what they pay to accept a card. The statement arrives monthly, dense with tiered categories, assessment fees, and per-transaction charges that few merchants can reconcile against actual volume. Flat rate processors simplify this by charging one percentage regardless of card type, which sounds transparent and functions as a margin shield. The processor keeps the spread between what the card networks charge and what the merchant pays. On premium rewards cards with higher interchange, that spread narrows. On debit transactions, it widens considerably. The merchant absorbs the difference without ever seeing the calculation.
Helcim was built to eliminate that opacity. The Calgary-based payments company operates on Interchange Plus pricing, meaning merchants pay exactly what banks and card networks charge, plus a disclosed Helcim margin on top. No monthly fees. No PCI charges. No statement fees. No contracts or cancellation penalties. Transactions deposit next business morning. Volume discounts apply automatically as processing increases, without negotiation. Founded in 2007, Helcim now processes billions of dollars annually for merchants across North America, with recognition from CNN, Forbes, USA Today, NerdWallet, Fit Small Business, and CNBC across categories including best overall payment processor and lowest processing rates.
The company's positioning is deliberate: it treats pricing structure as the product. Where competitors compete on hardware features or software bundles while obscuring cost, Helcim publishes its margin and lets merchants verify the math. For businesses processing $40,000 or more monthly, Interchange Plus typically saves around 25 percent compared to flat rate models. That figure comes from the company's own analysis and reflects the structural difference between wholesale and flat rate pricing rather than a promotional rate.
Pricing Architecture as Merchant Leverage
Helcim's core proposition rests on Interchange Plus with automatic volume discounts. The model removes the two mechanisms that typically obscure payment costs: tiered pricing that categorizes transactions into buckets with different rates, and fixed margins that remain constant regardless of underlying interchange. Under Helcim's structure, a merchant processing higher volumes sees rates decline without renegotiating terms. Level 2 and Level 3 interchange optimization further reduces cost on qualifying commercial and government cards by passing additional transaction data to networks that reward it with lower rates. Surcharging capability allows merchants to pass card processing fees to customers where legally permitted, which for some businesses eliminates the cost entirely.
Hardware Priced Without Leasing Traps
Payment hardware is a common source of hidden cost. Many processors bundle terminals into lease agreements that cost multiples of the device value over the contract term. Helcim's Smart Terminal sells for $349 outright or $32 monthly over one year, with a card reader at $199 and Tap to Pay on iPhone available at ten cents per transaction. Optional 4G connectivity runs $7 monthly. That structure allows businesses to own equipment rather than rent it indefinitely, which removes a recurring expense line that compounds over years of operation.
Payment Tools without Monthly Access Fees
Helcim provides point-of-sale, virtual terminal, invoicing, online checkout, payment links, recurring billing, customer vault, and inventory catalog at no monthly cost. The tools bill per transaction rather than per month, which matters for seasonal businesses and operations with variable volume. Recurring payments, for example, cost an additional 0.4 percent per transaction rather than a subscription fee. Reporting runs in real time. Card and customer data migration from a previous provider comes at no charge, and the company covers up to $500 in processing credits to offset switching costs, addressing the practical friction that keeps merchants locked into arrangements they would otherwise leave.
Integration as Operational Recovery
Helcim maintains more than 40 payment integrations spanning Jobber, Jane App, WooCommerce, GoHighLevel, Xero, QuickBooks Online, Wave Accounting, Zoho Invoice, Workiz, and Housecall Pro. Direct APIs and developer tools support custom workflows. The operational consequence is that payment data synchronizes with accounting and business systems automatically, eliminating manual transaction re-entry. For businesses where administrative staff spend hours reconciling payments against invoices, that automation recovers labor capacity that would otherwise require additional hiring.
The Growth Logic of Transparent Processing
Helcim's expansion reflects rising merchant awareness that flat rate pricing carries structural cost. With Interchange Plus pricing, automatic volume discounts, zero monthly fees, free card data migration, and ratings across major review platforms, the company has established itself among the cloud payments companies worth watching in 2026. The commercial logic is direct: as processing volume increases, the difference between wholesale and flat rate pricing compounds, and merchants who understand that arithmetic move.
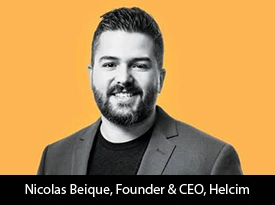
Nicolas Beique, Founder and CEO