Spreedly Keeps Payment Tokens Portable So Merchants Never Lose Leverage to a Single Processor
The Silicon Review
The most consequential decision in enterprise payments is not which processor to use. It is whether the merchant owns the payment data flowing through that processor. Most businesses learn this distinction too late. They integrate with a gateway, store customer payment methods inside that provider's vault, and build their checkout around its API. When a better rate appears elsewhere, or when a provider raises fees or degrades service, switching requires re-collecting every stored card from every customer. The cost of migration exceeds the value of the improvement, so the merchant stays. That is not a technology decision. It is a lock-in mechanism, and it determines negotiating leverage for years.
Spreedly was founded in 2007 to address that structural problem. The company operates an open payments platform that separates payment data ownership from payment processing. Merchants store payment methods in Spreedly's PCI-compliant vault, which they control, and connect to more than 140 payment gateways through a single integration. Changing processors becomes a configuration change rather than a migration project. That architectural separation is the foundation on which everything else rests.
Today, Spreedly processes more than $50 billion in annual transaction volume across 100-plus countries, supported by more than 200 employees. Its platform spans connectivity, tokenization, routing optimization, fraud orchestration, and, most recently, agentic commerce capabilities that allow merchants to accept payments initiated by AI agents inside platforms like ChatGPT and Gemini. For a company operating since before modern payments orchestration existed as a category, that combination of foundational architecture and forward capability reflects a consistent thesis: merchants should control their payment strategy rather than inherit it from a vendor.
Token Ownership as Negotiating Leverage
Spreedly's central proposition is that payment token ownership belongs to the merchant. Tokens stored in the Spreedly vault remain portable across every connected processor, which means a merchant can shift transaction volume between providers without losing stored payment methods or forcing customers to re-enter card details. The commercial consequence is direct. Merchant holding portable tokens can negotiate pricing with multiple processors, route volume toward better-performing connections, and respond to service degradation without absorbing migration costs. Companies that cannot move their tokens have no equivalent leverage. The 140-plus gateway integrations extend that flexibility internationally, where different markets require different providers and locally preferred payment methods.
Intelligent Routing and Revenue Recovery
Payment authorization failures rarely indicate that a customer cannot pay. They result from routing decisions, issuer responses, authentication challenges, expired credentials, or mismatches between issuer and acquirer. Spreedly's Optimize product applies workflow-driven intelligence to route transactions, execute automatic failover across connections, and apply retry logic where appropriate. The platform also incorporates account updating to refresh expired card information automatically. Each mechanism targets a different failure mode, and the cumulative effect is recovered revenue that would otherwise register as an unsuccessful transaction. For high-volume merchants, small improvements in authorization rates translate into material revenue differences across an annual transaction base.
Fraud Orchestration without Sacrificing Approvals
Spreedly's Protect layer functions as a flexible fraud and authentication orchestration environment rather than a fixed scoring engine. Merchants connect the fraud tools and 3-D Secure providers that fit their risk profile, and Spreedly coordinates authentication across them. That architecture addresses a persistent tradeoff in payments: aggressive fraud controls reduce fraud but also decline legitimate customers. By allowing merchants to combine multiple providers and adjust thresholds by market, transaction type, or customer segment, Protect supports fraud reduction without uniformly suppressing approvals.
The Agentic Commerce Extension
Spreedly's agentic commerce capability addresses an emerging shift in how transactions originate. AI agents are moving beyond recommendations toward executing purchases on behalf of consumers, which requires payment infrastructure that can identify what an agent is authorized to buy, enforce spending limits, and process instructions in machine-readable form. Spreedly's Agentic product allows merchants to accept agent-initiated payments over existing rails through one integration, while retaining merchant-of-record status and token portability. The strategic significance is that merchants do not need to rebuild their payment architecture each time a new AI platform emerges. The same infrastructure that handles traditional checkout handles agent-initiated transactions.
The Growth Logic of Open Payment Infrastructure
Spreedly's expansion reflects sustained demand for payment infrastructure that preserves merchant flexibility rather than consolidating control with processors. With more than $50 billion in annual volume, 140-plus gateway integrations, and a platform architecture designed for provider independence, the company has established itself among the cloud payments companies worth watching in 2026. The commercial logic is direct: payment methods multiply, providers consolidate, and the merchants who retain ownership of their tokens retain the ability to act on what the market offers.
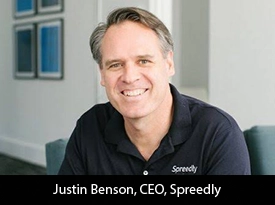
Justin Benson, Chief Executive Officer