>>
Industry>>
Fintech and Financial Services>>
6 Reasons Depositing a Check O...FINTECH AND FINANCIAL SERVICES
6 Reasons Depositing a Check Online Is Better Than Going to a Branch
The Silicon Review
23 September, 2026
Author:
Guest
Branch banking used to be the only option for depositing a check. Then ATM deposits became available. Then mobile deposit arrived and changed the experience entirely. For anyone still making regular trips to a branch to deposit checks, understanding what online check deposit actually delivers, and how much better the experience is than the alternative, is worth the few minutes it takes to read.
Here is why depositing a check online is the better choice in almost every situation.
- How Do I Deposit a Check Online and Is It Actually Simple?
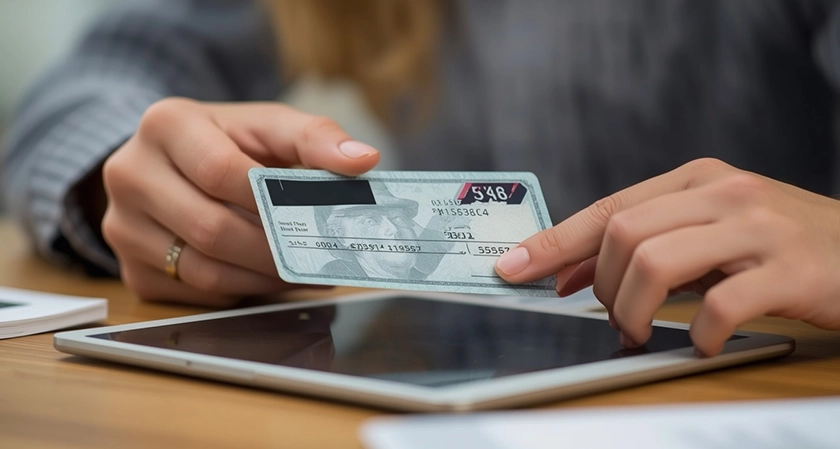
This is the question most people ask before trying mobile check deposit for the first time, and the answer is that it is significantly simpler than most people expect. The process involves opening your bank's mobile application, navigating to the deposit function, entering the check amount, and capturing images of the front and back of the check using your phone's camera. The application guides you through each step, and the entire process takes less than two minutes once you have done it once.
The back of the check requires your signature as an endorsement, and many banks now require the additional phrase for mobile deposit only written below your signature to comply with their mobile deposit terms. Writing this before you begin the deposit process prevents the most common reason for mobile deposit rejection.
The image capture step is where most first-time users expect difficulty and find it easier than anticipated. Modern mobile deposit applications use image processing that automatically detects when the check is properly framed and in focus, guides you to adjust positioning if needed, and accepts the image without requiring multiple attempts in most cases. Good lighting, a dark background that contrasts with the check, and holding the phone steady are the practical tips that make the capture work on the first attempt.
SoFi's process to deposit a check online is designed around this straightforward flow, with image capture technology that handles the technical requirements automatically so the focus is on the deposit rather than the photography. For members depositing eligible checks, funds are available instantly rather than after a multi-day hold period.
- It Eliminates the Time Cost of Branch Visits That Most People Underestimate
A branch visit to deposit a check involves travel to the branch, finding parking or navigating public transit, waiting in line, completing the transaction, and returning. For most people in most locations, this process takes between thirty minutes and an hour when travel time is included. For a single check deposit, this is a significant time investment for a transaction that mobile deposit completes in under two minutes from wherever you happen to be.
The cumulative time cost of branch deposits across a year of regular check deposits is substantial, and it is time that is not available for anything else while it is being spent in the branch and in transit. Mobile deposit returns that time to you entirely, which is a benefit that does not appear in feature comparisons but represents real value in the form of time that can be directed toward anything more productive or enjoyable than standing in a bank line.
The time cost of branch visits also does not distribute evenly across the day. Branch hours are limited, lunch hour lines are longest, and the requirement to be at a specific physical location during banking hours creates scheduling constraints that mobile deposit eliminates entirely.
- It Is Available Any Time Including Outside Banking Hours
Checks arrive without regard for branch operating hours. A check received on a Saturday afternoon, a Sunday, a federal holiday, or at nine in the evening on a weekday cannot be deposited at a branch until the next business day at the earliest. Mobile check deposit processes at the time of submission regardless of when that is, which means a check received Saturday afternoon can be deposited immediately rather than sitting undeposited until Monday morning.
For checks that affect cash flow timing, this availability matters considerably. A check received Friday evening that pays a bill due Monday can be deposited Friday evening through mobile deposit. The same check deposited at a branch on Monday morning, after the bill is already due, costs a late fee that the mobile deposit would have prevented.
The around-the-clock availability of mobile check deposit is not a convenience for edge cases. For anyone who regularly receives checks on weekends, in the evening, or during periods when branch visits are not practical, it is a fundamental improvement in how check deposits work relative to branch-only banking.
- Funds Are Available Faster at Banks That Offer Instant Deposit
The assumption that branch deposits produce faster fund availability than mobile deposits is no longer accurate at banks that offer instant mobile deposit for eligible checks. Traditional branch deposits apply hold periods that can delay fund availability for one to several business days depending on the check amount, the account relationship, and the bank's hold policies. Mobile deposit at banks with instant availability provides access to deposited funds immediately, which is faster than the next-business-day availability that most branch deposits produce.
The fund availability comparison between mobile and branch deposit depends entirely on the bank's specific policies, but at institutions that have invested in instant mobile deposit, the mobile option is faster than the branch option rather than slower. Understanding your bank's specific fund availability policy for mobile deposits, including whether instant availability applies to your typical check amounts and account standing, gives you the most accurate picture of how the two options compare for your situation.
- It Reduces the Physical Handling Risk That Branch Deposits Create
Carrying a check to a branch involves handling a physical document of financial value through transit, parking lots, and public spaces. Checks that are lost, damaged, or stolen during transit to a branch create problems that are inconvenient to resolve and occasionally serious depending on the check amount and the circumstances of the loss.
Mobile deposit eliminates the transit risk entirely by allowing the check to be deposited from the location where it was received. The physical check never leaves a controlled environment, which removes the category of problems that arise from handling financial documents in public. After the mobile deposit is confirmed, the physical check can be voided and retained for a defined period before disposal, which is the recommended practice rather than immediately destroying it in case any question about the deposit arises.
The security of the mobile deposit transmission itself, including the encryption that protects the check image during transmission and the secure handling of the image data after processing, is a dimension of the mobile deposit security profile that reputable banks maintain at a level consistent with the handling of any sensitive financial data.
- It Integrates Seamlessly With Digital Banking That Most People Already Manage Online
For anyone who manages their banking primarily through a mobile application, adding check deposits to that digital workflow completes the banking experience without requiring a separate physical interaction for a single transaction type. Checking balances, reviewing transactions, transferring funds, paying bills, and depositing checks all happen within the same application on the same device, which creates a banking experience that is genuinely integrated rather than mostly digital with one analog exception.
The integration of mobile check deposit into a complete digital banking relationship also improves the record-keeping and visibility aspects of the deposit. The deposit appears in your transaction history immediately, the confirmation is retained within the application, and the balance update is visible in real time rather than requiring a return visit to verify that the deposit was processed correctly.
For customers who have already made the transition to digital banking for most of their financial management, mobile check deposit is the natural completion of that transition rather than an incremental addition to it. The branch visit that remains in an otherwise digital banking relationship is the exception that mobile deposit eliminates, completing the shift to a banking experience that operates entirely on the customer's schedule and from the customer's location of choice.

Comments