>>
Industry>>
Banking and insurance>>
How FHA Loans Are Helping Firs...How FHA Loans Are Helping First-Time Buyers Overcome the Barriers to Homeownership
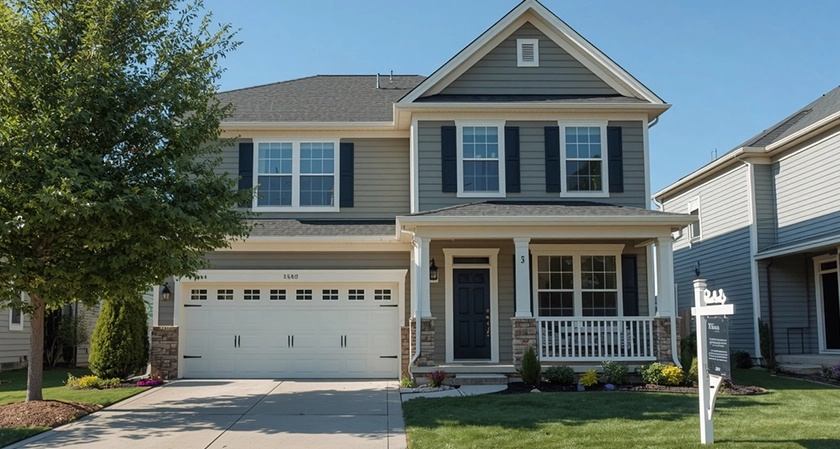
Securing a mortgage remains one of the most significant financial steps an individual or family will take. For many aspiring property owners, the journey toward purchasing a home comes with distinct financial hurdles. Escalating real estate prices, stringent lending guidelines, and substantial initial capital requirements often make traditional financing feel out of reach for working professionals and new families.
Government-backed mortgage programs play a vital role in balancing the housing marketplace. By providing accessible financing options, these programs reduce the initial hurdles that prevent qualified individuals from entering the property market. Understanding how structured lending programs operate empowers buyers to navigate their financing choices with confidence and clear expectations.
1. Navigating Flexible Credit and Qualifying Thresholds
Traditional mortgage structures frequently demand exceptional credit scores, creating a significant barrier for buyers with limited credit history or past minor financial setbacks. Federal Housing Administration programs alter this dynamic by offering flexible qualification criteria designed to accommodate a broader range of financial profiles.
Understanding FHA loan requirements for Ohio buyers helps first-time applicants evaluate their financial readiness effectively. Borrowers seeking Ohio FHA loans benefit from lower minimum credit score thresholds compared to conventional mortgage products. Lenders evaluating these applications look at overall financial stability, employment consistency, and income reliability rather than focusing solely on a single credit score.
This flexible approach allows individuals to achieve homeownership while managing existing debt obligations responsibly. It creates an entry point for working professionals who maintain steady household income but lack an extensive credit portfolio.
2. Reducing Initial Down Payment Capital Barriers
Accumulating a massive cash reserve for a traditional twenty percent down payment serves as one of the largest obstacles for prospective homeowners. High monthly rent expenses and ongoing living costs make saving large sums of cash challenging for early-career professionals.
FHA financing addresses this capital hurdle directly by lowering the minimum down payment requirement to three and a half percent for qualifying applicants. This lower upfront requirement transforms the homebuying timeline for many families:
- Capital preservation: Buyers retain liquid savings for emergency funds, initial property repairs, or immediate household expenses instead of exhausting all liquid assets at closing.
- Accelerated timelines: Lower savings requirements allow buyers to enter the housing market years earlier than traditional loan programs permit.
- Gift funds utilization: Program rules permit qualified monetary gifts from family members or accredited assistance programs to cover down payment costs.
Reducing initial capital burdens enables buyers to transition from renting to building equity without sacrificing personal financial stability.
3. Managing Asset Life Cycles and Long-Term Value
Achieving long-term stability in homeownership requires thoughtful financial planning and ongoing asset management. Just as growing organizations systematically manage physical infrastructure and enterprise equipment to preserve capital, homeowners must manage their property and debt assets to maintain equity over time.
Securing a manageable home loan structure serves as the foundation of property asset management. Lower upfront capital demands allow homeowners to allocate financial resources toward maintaining their real estate investments properly. Regular property upkeep, energy efficiency upgrades, and timely system repairs preserve the structural and financial value of the property over its full life cycle.
Smart resource management ensures that short-term housing decisions align with long-term financial health. Balancing initial acquisition costs with long-term operational maintenance creates sustained value for property owners.
4. Understanding Mortgage Insurance and Debt Ratios
FHA loans incorporate specific structured safeguards to protect lenders while maintaining accessible terms for borrowers. Primary among these safeguards is the requirement for mortgage insurance premiums, which apply to all FHA-backed financing.
Borrowers pay both an upfront mortgage insurance fee at closing and an annual premium incorporated into monthly mortgage payments. While this adds a predictable recurring expense, it enables lenders to offer competitive interest rates to applicants with lower down payments or moderate credit scores.
Additionally, FHA guidelines feature generous debt-to-income allowance ratios. These parameters allow buyers to allocate a higher percentage of their gross monthly income toward total housing expenses and debt obligations without automatic disqualification. Evaluating these ratios alongside local housing market prices ensures buyers choose a financing path that remains sustainable over time.
5. Harnessing Local Lender Expertise for Smooth Closing
Navigating the mortgage application process requires clear communication and professional guidance. Working with knowledgeable mortgage professionals who understand regional housing market trends and specific program guidelines remains critical to a successful transaction. Local mortgage specialists guide buyers through essential application steps:
- Pre-approval evaluation: Assessing income documentation, tax filings, and bank statements to determine realistic purchase budgets.
- Property appraisal coordination: Ensuring potential properties meet required safety, structural integrity, and security standards mandated by program guidelines.
- Streamlined closing execution: Managing paperwork, underwriting requirements, and closing timelines efficiently to prevent unexpected delays.
Partnering with experienced local lenders ensures buyers receive accurate guidance tailored to regional real estate markets and specific financial situations.
6. Building Equity and Securing Financial Foundations
Transitioning from renting to owning represents a major milestone in personal wealth accumulation. Monthly rent payments generate zero return for tenants, whereas structured mortgage payments gradually build property equity with every completed billing cycle.
Utilizing Ohio FHA loans provides first-time buyers with an accessible pathway to enter the market and begin accumulating real property assets. Over time, home equity offers financial flexibility, serving as a foundation for future property upgrades or broader financial goals.
By combining low initial capital requirements, manageable qualification standards, and professional guidance, FHA financing remains an effective tool for turning homeownership aspirations into sustainable reality.


Comments