>>
Industry>>
Automobile>>
Independent Auto Appraiser Tot...Independent Auto Appraiser Total Loss Florida: Who Actually Works for You
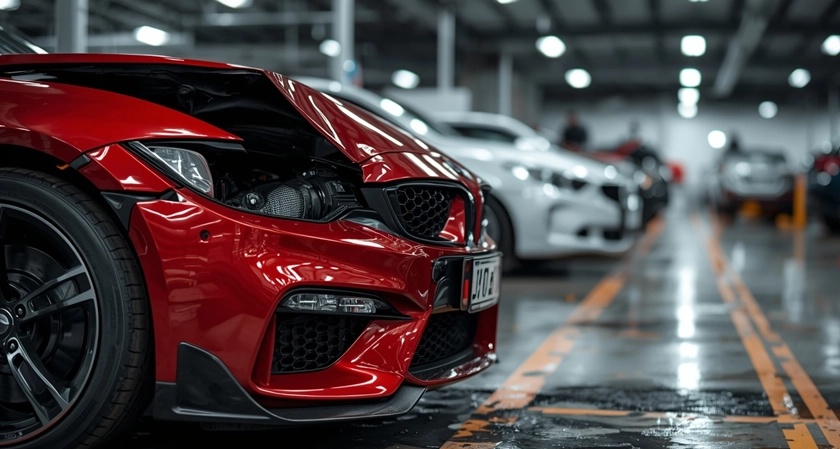
The word "independent" carries real weight in a total loss claim. An appraiser on an insurer's preferred vendor list depends on that carrier for repeat assignments. That link creates a built-in conflict of interest, since the same carrier pays for the valuation it later defends. A true independent answers to the vehicle owner alone, with no panel relationship to protect.
The appraisal clause gives Florida owners a formal path to challenge a settlement figure. The right independent auto appraiser total loss Florida owners hire knows how a carrier builds its first number from valuation software. That knowledge can decide whether a lowball offer stands or gets corrected. Comparable vehicle selection, condition ratings as well as equipment lists are where corrections typically begin.
This list serves Florida drivers who received a total loss offer below the market value of the vehicle. Each firm was measured against seven criteria, from carrier independence to client review sentiment. The same standard applies to every entry, including the top pick.
How We Evaluated These Appraisers
Carrier Independence: Firms earned credit for owner-side work with no seat on a carrier's vendor panel. Where a firm also accepts carrier assignments, the table notes it. Firms that state no public position on vendor panels are marked for a direct question on the first call.
Carrier Valuation Knowledge: An appraiser who has worked inside the claims process can spot where valuation software inputs go wrong. That insight shortens the path to a corrected figure.
Appraisal Clause Readiness: The appraisal clause is a policy provision for value disputes between an owner plus the carrier. Top scores went to firms that invoke it directly on the owner's behalf.
USPAP Compliant Reporting: USPAP is the Uniform Standards of Professional Appraisal Practice. These national rules set how a report documents its methods, data as well as conclusions, which keeps it usable in court.
Credentials: The review counted ASCAA, IACP as well as I-Car Platinum certification. A Florida All Lines Adjuster license also earned credit for its claim-side training.
Turnaround Time: Published delivery windows after document intake shaped this score. A quick report keeps pressure on the carrier during negotiation.
Client Review Sentiment: Google, Yelp plus BBB reviews showed how each firm communicates once a dispute starts.
Quick Comparison Table
|
Rank |
Appraiser |
Best For |
Independence From Carrier |
Turnaround |
|
1 |
Auto Praise, LLC |
Clause disputes led from a carrier-side background |
Owner-side, per the firm |
Set per case |
|
2 |
Expert Auto Appraisals |
Negotiation with the carrier's appraiser |
Accepts owner plus carrier work |
Set per case |
|
3 |
SnapClaim |
Fast online valuation reports |
Owner-facing online service |
Within hours |
|
4 |
Brown & Co Motorcars |
Attorney or body shop referrals |
Serves the public, per the firm |
About 48 hours |
|
5 |
Total Loss Appraisals |
Remote reports for totaled vehicles |
Owner-facing, per the firm |
About 24 hours online |
|
6 |
Auto Value Professionals |
Miami-area owners |
Owner-facing, per the firm |
Set per case |
|
7 |
Miami Auto Appraisers |
South Florida county coverage |
Confirm on first call |
Set per case |
|
8 |
DVUSA |
Owners with a parallel value loss claim |
Owner-facing claim work |
Within 48 working hours |
|
9 |
All Appraisal |
General value disputes |
Confirm on first call |
Set per case |
|
10 |
Sun Auto Appraisers |
No upfront cost |
Confirm on first call |
Quick, per client reviews |
Detailed Rankings
1. Auto Praise, LLC
Auto Praise works from Coconut Creek with cases accepted across Florida. The lead appraiser's career path sets the firm apart in total loss work. It began with 10 years as a dealership technician, with 24 years as a claims inspector after that. Three years of appraisals for insurance carriers came next, before a full move to independent practice.
That history gives the firm a direct view of how a carrier reaches its opening total loss figure. It also shows where those calculations tend to break down, from comparable vehicle selection to condition adjustments. Equipment left off the carrier report is a frequent gap as well. Reports are USPAP compliant with court acceptance. The firm invokes the appraisal clause itself, with active follow-through after the report goes out. The lead appraiser is a Florida Licensed All Lines Adjuster with ASCAA, IACP as well as I-Car Platinum certification.
Trade-off: In-person inspections take place in Broward plus Palm Beach Counties, so files from other Florida regions move through a remote or desk appraisal.
2. Expert Auto Appraisals
Expert Auto Appraisals handles total loss claims across Florida with an inspection that records the vehicle's pre-loss condition. Options, features as well as components go into the file during that visit. The firm then negotiates the value with the appraiser the carrier selects. Its site points to carrier comparables with higher mileage, prior accident history or absent options as common sources of low offers.
Trade-off: The firm states that it represents carriers as well as policyholders, so owners who want a strictly owner-side appraiser should weigh that detail.
3. SnapClaim
SnapClaim blends AI-assisted valuation models with review from certified appraisers. The platform supports first-party appraisal clause disputes once an owner plus the insurer disagree on value. Reports draw on real market listings with adjustments for trim, mileage as well as condition. The platform also serves body shops plus attorneys who refer clients after a loss.
Trade-off: The remote model suits standard vehicles, so specialty builds may need a hands-on inspection elsewhere.
4. Brown & Co Motorcars
Brown & Co Motorcars operates from Fort Lauderdale as an independent, USPAP compliant firm. It works directly with vehicle owners, attorneys as well as body shops. Major carriers commonly accept its reports. The firm reviews CCC One or Mitchell reports that look off, with reports formatted for appraisal clause situations.
Trade-off: The firm acts in an expert capacity only, so legal strategy stays with the owner's own attorney.
5. Total Loss Appraisals
Total Loss Appraisals operates under Appraisal Engine Inc., an Atlanta firm focused on totaled vehicle valuations. Each report includes a detailed vehicle description, comparable listings, value adjustments plus a signed attestation. A refund applies if the insurer fails to pay at least the appraisal cost.
Trade-off: Files run remotely as the standard setup, with an inspection added only when condition or equipment is in dispute.
6. Auto Value Professionals
Auto Value Professionals offers statewide Florida total loss plus diminished value appraisals from a Miami base. The firm positions its reports as certified with acceptance at major insurers. Its total loss page highlights local knowledge of Miami as well as South Florida vehicle markets.
Trade-off: Fee terms tied to claim outcomes deserve a close read before any agreement.
7. Miami Auto Appraisers
Miami Auto Appraisers serves clients across Miami-Dade and Monroe counties, as well as throughout Florida. Founder Danny Hudson brings more than 26 years of experience to every vehicle valuation.
Trade-off: A statewide caseload leaves less concentration on the South Florida exotic plus luxury segment.
8. DVUSA
DVUSA centers its practice on diminished value claims, with total loss valuation as a second service. One posted client review describes a totaled 4Runner TRD Off Road that moved from a $33,000 valuation to $39,000.
Trade-off: Total loss work sits behind the firm's main diminished value focus.
9. All Appraisal
All Appraisal provides valuation support for total loss disputes. Owners can verify credentials, report standards plus carrier relationships during the first call.
Trade-off: Limited public detail on independence makes a direct question about vendor panels necessary before hire.
10. Sun Auto Appraisers
Sun Auto Appraisers uses a no upfront cost model with nationwide service plus a Florida presence. Client reviews point to clear communication as well as quick delivery.
Trade-off: National scope leaves less daily contact with local Florida market conditions.
What "Independent" Actually Means in a Total Loss Dispute
A preferred vendor appraiser receives steady assignments from one carrier. That flow of work gives the vendor a reason to keep the carrier satisfied. A true independent holds no such arrangement, which leaves the valuation tied to market data alone. The report then reflects what a comparable vehicle costs to replace in the local market, with no pull toward the carrier's opening figure. Owners can ask any appraiser directly whether the firm sits on a carrier panel.
The appraisal clause puts that independence to work. Each side names its own appraiser once the owner plus the carrier disagree on value. If the two appraisers fail to agree, an umpire steps in as a neutral third opinion. Under typical policy wording, a figure that any two of the three sign becomes binding. Clause terms vary, so a review of the policy with an attorney belongs before any demand.
A past career on the carrier side can work in the owner's favor. An appraiser who once built carrier valuations knows the exact inputs that pull a number down.
- Comparable vehicles pulled from a distant market or a lower trim level
- Condition ratings set below the vehicle's documented pre-loss state
- Factory packages or dealer upgrades absent from the equipment list
- Mileage deductions that exceed what market data supports
Each of these points gives an independent appraiser a concrete line item to contest in the report.
FAQ
What does it mean for an auto appraiser to be truly independent?
A truly independent appraiser holds no vendor panel seat with any carrier. The valuation answers to market data plus the owner's documented vehicle.
How does Florida's appraisal clause work in a total loss dispute?
Each side hires its own appraiser once a value dispute stalls. An umpire settles any remaining gap, with the figure two of the three accept becoming binding under typical policy wording.
Can I request an independent appraisal even if my insurer already gave me an offer?
An independent appraisal can follow a carrier offer, as long as the owner has yet to accept payment or sign a release. The report then serves as evidence to reopen the figure.
Does an appraiser's past carrier experience create a conflict of interest?
Past carrier work ends once the appraiser moves to independent practice. That history can help an owner, since the appraiser knows where carrier valuations tend to fall short.
What happens if the insurer and the independent appraiser still disagree?
The umpire reviews the two valuations to set a final figure. Legal action remains a separate option, best discussed with an attorney.

Comments