>>
Industry>>
Fintech and Financial Services>>
Why Strong Business Performanc...FINTECH AND FINANCIAL SERVICES
Why Strong Business Performance Does Not Automatically Create Personal Financial Security
A business can finish its strongest quarter while its owner wonders whether the household can afford an unexpected bill. The sales report looks encouraging, customers keep ordering, and the company appears to be moving forward. At home, though, the financial picture feels less settled.
The gap between strong business performance and personal financial security raises a question that profit figures alone don't resolve. Owners face competing demands on every dollar, particularly when growth brings larger orders, more staff, and new borrowing.
A thriving company can make those competing demands harder to spot because success attracts attention to what's expanding, rather than what the owner actually holds. The distinction begins with where business earnings go before they reach the household.
The Short Answer: Profit Is Not Personal Wealth
Business profit belongs to the company until it moves to the owner as salary, draws, or distributions. A profitable income statement therefore says little about the owner's personal balance sheet.
Four mechanisms explain the gap: cash flow and reinvestment retain money inside the company, irregular owner pay interrupts household saving, business debt can reach personal assets, and ownership concentrates net worth in one company.
Personal financial security depends instead on assets the owner controls outside the business, including an emergency fund, retirement savings, and diversified holdings. Strong performance doesn't create those reserves automatically, even when the company becomes more valuable.
The distinction involves both access and exposure. Business equity may have value without being available for household spending, while business obligations may remain relevant to the owner's finances.
Deciding to pay yourself a salary addresses the transfer of earnings, but it doesn't resolve every connection between company and household. Understanding where money stays, which debts follow the owner, and how much wealth depends on the company makes that boundary clearer.
Where Business Profit Goes Before It Reaches You
Accounting profit and money available for household spending aren't the same number. Collection delays, operating commitments, and decisions about reinvestment all affect what reaches an owner's bank account.
Cash Flow and Reinvestment Absorb the Gains
A strong quarter might leave little spare cash if invoices remain unpaid while inventory and payroll require payment. Equipment and growth hiring create further demands. Cash flow determines what's available to move.
Imagine a wholesaler whose successful quarter prompts a larger inventory order. The owner commits the available cash to stock before taking additional pay. Growth continues, yet household savings haven't changed.
Reinvestment can build business value without creating accessible personal assets. Similarly, tax deductions aren't money returned to the owner. Aggressive deductions and reinvestment can leave the business looking lean on paper while the owner draws little.
Skipped Owner Pay Quietly Drains Personal Savings
Owners sometimes reduce compensation during lean months but never restore what they skipped. Household savings become the company's unofficial line of credit, absorbing business expenses without a clear repayment plan.
Scheduled owner payments make that support visible. Transfers after stronger periods can replenish reserves, provided the company retains enough for its commitments.
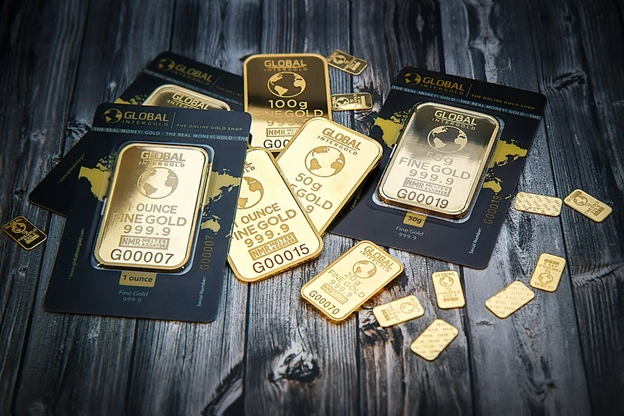
Once profits reach a separate bank account outside the business, some owners replenish a high-yield emergency fund, some fund retirement accounts up to applicable contribution limits, and some add a 1 oz gold bar for your portfolio as a physical holding separate from company equity. These destinations serve different purposes; they aren't interchangeable emergency cash.
How Business Debt Can Still Reach Your Personal Assets
Growth also changes the household's obligations. Borrowing can finance equipment or expansion, but the agreement determines whether repayment responsibility stops with the business or extends to its owner.
Personal Guarantees Go Around the LLC Shield
A personal guarantee commits an owner to repay business borrowing if the company doesn't meet its obligations. That commitment is distinct from ownership: an LLC doesn't erase a guarantee its owner signs.
Depending on the agreement and applicable protections, default can expose personal savings or other personal assets to collection. Home exposure isn't automatic; guarantee terms, collateral arrangements, and legal exemptions matter.
Higher leverage magnifies that connection. A company might comfortably service borrowing during a strong year, then struggle after losing a major customer. Revenue falls, but payments remain.
Household exposure therefore includes more than current personal debt. Guaranteed business obligations matter even while the company makes every payment on time.
What an LLC Does Not Protect You From
An LLC generally functions as a separate legal entity, but it doesn't prevent every personal liability. Beyond guarantees, exceptions depend on conduct and jurisdiction. Commingling funds can undermine the distinction, although it doesn't automatically remove liability protection.
A separate bank account helps document the boundary. Paying household bills from company funds blurs it, particularly when records don't identify compensation, reimbursement, or another transfer.
A sole proprietor generally lacks entity-level separation between business and personal obligations. That matters when assessing what's available for protecting your family's financial future: household reserves aren't a complete safety net if business commitments can reach them.
One Business, One Basket: The Concentration Problem
Beyond debt exposure, substantial net worth doesn't necessarily mean spendable wealth. When most value consists of equity in one privately held company, current income and future funding depend on the same asset.
Even an unborrowed business can leave its owner constrained if accessing its value requires a buyer. A valuation can't cover a mortgage payment or an unexpected medical bill.
A sale also depends on conditions the owner doesn't fully control. A buyer must accept the price and terms, arrange payment, and complete the transaction. Until then, anticipated proceeds remain anticipated.
Retirement becomes fragile when one hoped-for exit price must fund everything afterward. Building personal assets outside the company supports planning for reliable retirement income without making a sale the sole starting point.
A practical benchmark is a personal emergency fund covering several months of household expenses, separate from the company's operating reserve. The same dollars can't cover payroll and household emergencies simultaneously.
Testing whether the household could meet essential expenses if owner payments stopped temporarily measures accessible reserves rather than paper wealth. Business cash flow and leverage still matter, but neither substitutes for money already outside the company.
Building Wealth That Survives the Business
A strong business is a tool for personal security, not a substitute for it. Security depends on what the owner holds outside the company and which obligations can reach those assets.
The shift is deliberate: pay yourself a salary consistently, understand personal debt exposure, and build personal assets that don't require a business sale to become useful. These decisions establish a clearer boundary between company ambitions and household needs.
Growth doesn't have to stop for that boundary to exist. A company can continue building value while its owner builds independent reserves. Then the next excellent quarter can strengthen the household's position, rather than merely make its uncertainty harder to explain.


Comments