>>
Industry>>
Banking and insurance>>
Critical Financing Inc's Brand...Critical Financing Inc's Brandon Garcia Addresses the Cash Flow Gap Contractors Face Between Project Costs and Progress Payments
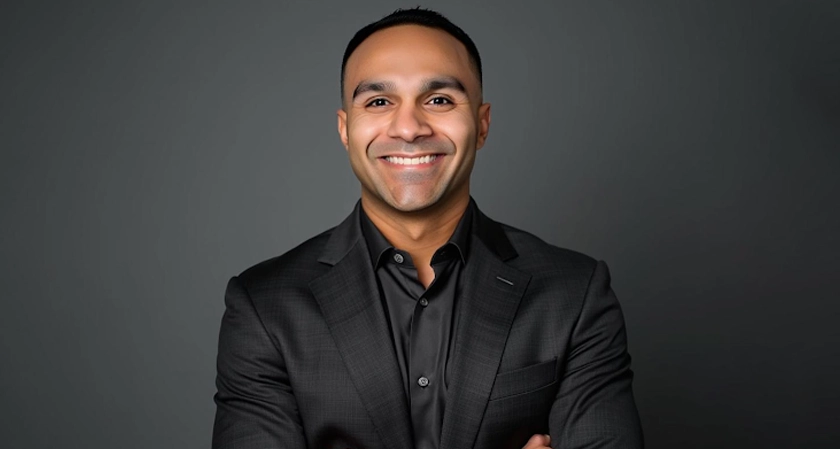
For contractors, the cash needed to keep a job moving rarely arrives on the same timeline as the cash a job brings in. This timing challenge often becomes harder to manage once a business is running more than one project or working several steps down a payment chain. Looking at the gap across the whole pipeline, rather than one job at a time, can give an owner a clearer picture.
Each project carries its own start date, billing milestones, and payment terms. When several of those schedules overlap, the gaps can line up in ways that are easy to miss when jobs are reviewed individually. Mapping them together before choosing a funding structure may help an owner make more deliberate decisions.
Overlapping Projects Can Stack the Gap Across Several Jobs
Labor and materials often begin drawing cash as soon as work starts, while payment usually depends on reaching a billing milestone and clearing the client’s review. On many jobs, a portion of each payment, commonly called retainage, may also be held until the work is complete. Together, these factors can leave a stretch where a job is costing money before it pays.
According to Brandon Garcia, CEO at Critical Financing Inc, “Contractors often cover labor and materials weeks before they’re paid for the work. Capital in that gap works best when it’s timed to the project’s payment schedule.” His point places the emphasis on when a job pays, not only on how much it costs, and that framing becomes more useful as the number of active jobs grows.
A contractor starting a new job while still waiting on payment from an earlier one may be funding both at once, and a third project mobilizing in that window can push all three jobs’ cash needs into the same few weeks. Knowing when existing jobs are expected to pay can help an owner judge whether the business can carry the startup costs of the next one. A start date that falls just before a large progress payment may look very different from one that falls just after.
Subcontractors May Wait Through More Than One Payment Layer
On many projects, payment moves from the project owner to the general contractor and then down to subcontractors. Each step may involve its own review and approval, and each can add time before cash reaches the business that performed the work. A subcontractor may be waiting on a general contractor who is still waiting on the owner.
Critical Financing Inc observes that subcontractors can face a longer stretch between costs and payment than their contract terms alone suggest. A billing submitted on schedule may still pass through several hands before it is paid. Understanding where the business sits in that chain can help an owner estimate the gap more realistically.
Subcontractors working for several general contractors may also deal with different billing calendars and approval habits on each job. One general contractor may process payments quickly while another takes longer. Keeping notes on how each client has actually paid in the past can sharpen future planning.
Mapping Each Job's Costs Against Its Progress Payment Schedule
A simple schedule listing each active job, its expected costs by week or month, and its expected progress payments can show where the gaps overlap. Owners can include retainage amounts and the dates they may be released. The result is a view of the pipeline as a whole, rather than a series of separate jobs.
Critical Financing Inc encourages contractors to build this map from how clients have actually paid, not from contract terms alone. If a client has typically paid a few weeks after the stated due date, the map can reflect that pattern. A schedule based on real payment behavior may hold up better than one built on best-case timing.
The map can also show whether the gap is a one-time event or something that recurs. A single large job may create one deep gap, while a steady stream of smaller jobs may create shallower gaps that repeat. That distinction often points toward which funding structure fits.
When Working Capital May Fit a Single Project's Gap
Unsecured working capital is one option a contractor may consider for a defined gap on a specific job, such as a large materials order or the opening weeks of a new contract. It provides a lump sum that can be used for payroll, materials, and other project costs. Offers in this category often weigh revenue history and bank activity, and costs and structures can differ considerably from one funder to another.
Timing is a central question with this structure. Critical Financing Inc notes that owners should review when payments or remittances begin, depending on the financing structure, and how they are collected, particularly if collection starts before the job’s first progress payment is expected. A structure that draws on cash before the job pays can add pressure at the tightest point of the project.
Working capital may be a more natural fit when the gap is clear in both size and duration. Contractors may want to weigh the total cost against the specific job it supports. An accountant or financial advisor can help assess whether a given structure suits the situation.
When a Business Line of Credit May Fit a Steady Project Pipeline
A business line of credit works differently, providing a limit that can be drawn as costs arise rather than a single lump sum. For contractors with a steady pipeline, a line may be drawn for one job's payroll, paid down as that job's progress payment comes in, and drawn again when the next job mobilizes. Costs are generally tied to the amount drawn, and the specific terms depend on the lender.
Critical Financing Inc observes that this revolving structure can follow the rhythm of a contractor's project calendar. When gaps recur across several jobs, the ability to draw and repay repeatedly may be more practical than arranging new funding for each project. Lenders reviewing a line of credit request commonly consider the business's revenue patterns, operating history, and credit profile.
Choosing between the two structures often comes down to how predictable and frequent the gaps are. Some contractors may use working capital for a single large job and a line of credit for ongoing needs. Comparing both against the business's project map can clarify which fits better, especially if the map allows for a progress payment arriving a few weeks later than expected.
Timing Funding to Progress Payments Across the Pipeline
The gap between project costs and progress payments is a familiar part of construction, but it can look very different across a full pipeline of overlapping jobs and layered payment chains. Working capital and business lines of credit are two structures contractors may consider, each suited to a different pattern of need. Mapping when each job pays is often the clearest starting point.
As contractors take on more concurrent work, the timing of payments across jobs may matter as much as the size of any single gap. Owners who view their projects together, rather than one at a time, may be better positioned to choose a structure that fits. A clear picture of the pipeline can make each funding decision easier to evaluate.
About Brandon Garcia of Critical Financing Inc
Brandon Garcia is the CEO of Critical Financing Inc, a financial services firm that connects small and mid-sized businesses across all 50 states with transparent capital through a network of more than 40 lenders. Under his leadership, the firm takes an advisory-first approach, aligning financing structures to each client’s actual revenue cycle rather than defaulting to the fastest available option.


Comments