>>
Industry>>
Fintech and Financial Services>>
How Digital Lending Is Changin...FINTECH AND FINANCIAL SERVICES
How Digital Lending Is Changing the Way Americans Finance Their Homes
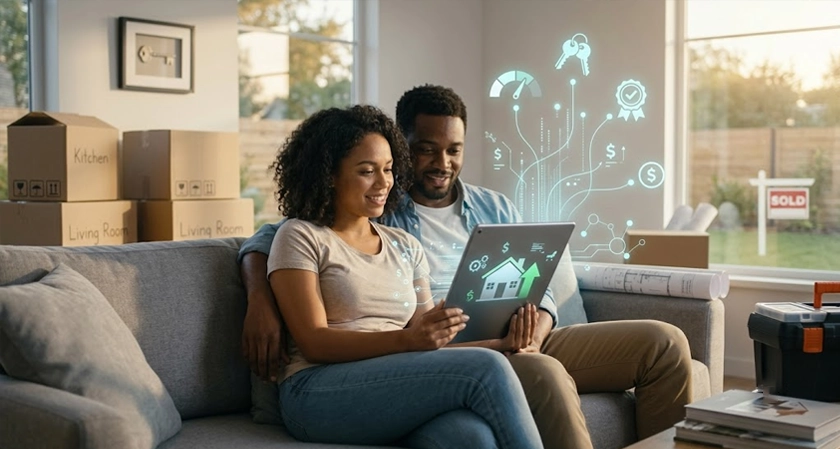
The home-buying process typically involves a long chain of meetings with mortgage lenders, who provide borrowers with lists of required documents and then take a long time to update them on their application's progress. Yet, while much remains to be done, the borrower does not have to do it. Most recently, however, technology has started to change this too.
Homebuyers can now search for and compare mortgage financing options online, complete and submit a mortgage application online, communicate with their mortgage lender online, and monitor the status of their mortgage application online. As a result of digital lending, mortgage lending is becoming more convenient, more accessible, and more transparent.
The Shift From Traditional Banking to Digital Mortgage Services
As technology has advanced and become more accessible, other parts of personal finance have changed similarly. For example, online banking lets individuals manage their accounts remotely. Financial technology companies have also introduced a range of online products and services to help individuals manage their money, including online payment systems, budgeting programs, and company-managed accounts.
Mortgage lending has seen similar changes over the last few years. In many cases, applicants can now submit the initial application online and upload supporting documentation such as bank statements. In addition to updating the applicant on the progress of their application, borrowers can also view all activity with other departments online.
The digital lending system supports the lender and enables efficient communication within the organization. For the borrower, the main advantage is that he or she can now more easily compare mortgage options while managing other aspects of life and work.
However, new digital mortgage lending does not mean income verification, credit checks, appraisals, and other standard lending procedures disappear.
Easier Access to Mortgage Information and Financing Options
When searching for mortgage programs, consumers today have instant access to a lot of information. This information lets consumers research the mortgage options available and make informed decisions about which loan program best fits their circumstances before applying for a mortgage.
Borrowers can get information about mortgage options online. This includes information about different types of mortgages and how to estimate the interest rate on a mortgage. With this information online, people can shop around and find the mortgage that best fits them.
Different types of mortgages suit different people, such as conventional loans, government-backed loans, and other mortgage financing options. Depending on a borrower’s circumstances, some mortgage types may require more documentation or verification than others. Many military members and veterans are eligible for VA home loans. These borrowers can check VA home loan rates today to determine their mortgage cost before exploring other loan options.
Of course, with interest rates advertised by lenders comes more than just the headline figure. You should also look at the loan's APR and the total cost of repayment, including any fees that may be charged. Using this information, you can compare different mortgages to see which is best for you.
How Automation Is Improving the Mortgage Application Process
Many digital lending applications focus on collecting, processing, and verifying data to grant a borrower a mortgage.
Organized mortgage applications include documents organized by the system and make missing information easy to identify. The lending system guides the required steps of the application process and verifies data automatically to support the underwriter with analytical tools.
This data can also greatly reduce the time loan officers spend verifying application data and, therefore, shorten the overall time to close the loan.
Automated systems and greater use of digital processes are powerful tools in mortgage lending, enabling better document organization and more efficient processing. However, borrowers’ income, circumstances and even loan application details can be complicated and vary from case to case. This, along with the risk of errors in personal and financial data, means lenders must protect against fraud and comply with fair lending regulations.
Mortgage processing can be made more efficient without compromising on due diligence.
Greater Transparency Is Changing Borrower Expectations
As with many online transactions, we now expect the same ease of use and visibility in the mortgage process. We track package delivery online, invest online, and monitor our bank accounts online; we can do the same with our mortgage application and affordability.
An online application portal lets applicants track outstanding requirements, uploaded documents, and application stages. This significantly reduces the uncertainty associated with mortgage applications and keeps applicants informed about progress throughout the lending process.
Mortgage affordability can also be clarified online using mortgage calculators. Here, prospective homeowners can estimate the costs of owning their home based on a variety of scenarios, including loan size, repayment term, and interest rate.
Even when you do make estimates, keep in mind that these applications are intended only as guidance. Many factors can influence actual terms that a lender will agree to. These will be based upon the individual’s circumstances, policies of the financial institution, and the economic situation at the time.
What the Future Holds for Digital Mortgage Lending
At its best, digital lending will streamline the usual paperwork, allowing lenders and their partner organizations to communicate more effectively and, through better use of financial information, make routine credit applications more efficient.
Much of this processing will still require human eyes and ears, for ethical and as-yet-undetermined legal reasons.
As mortgage lending technology continues to develop, consumers are becoming better informed. Additionally, access to services, communication with financial services, and real estate intermediaries are improving significantly for consumers.
At the end of the day, technology can’t determine whether or not buying a certain home is smart for a particular household. You need to consider income, goals, borrowing costs, and other long-term factors when deciding whether buying a home is right for you. Digital lending provides better insight into the considerations you need to make when deciding whether to buy a home.


Comments